You are earning well and have no time to manage it. We turn a strong income into lasting wealth, with less of it lost to tax.
Speak to an adviser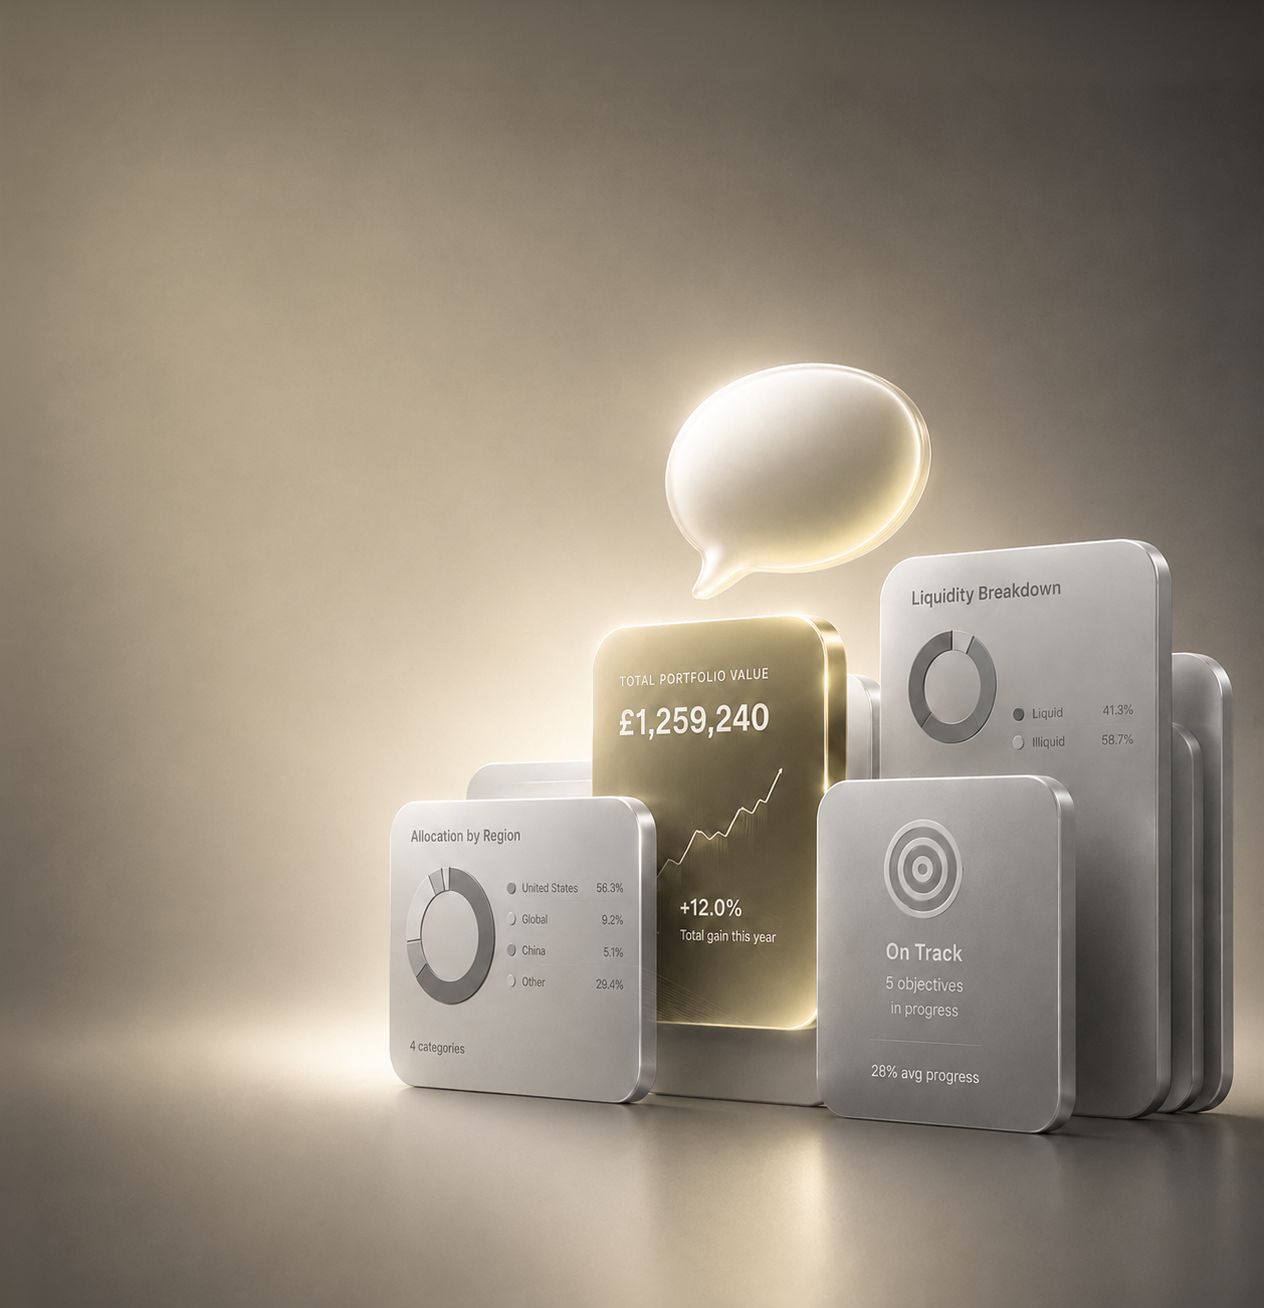
Six steps, from the first conversation to a plan that grows with your career. The first is a free half hour and commits you to nothing.
You tell us what you are earning, what you are trying to build and what is getting in the way. We tell you whether we can help, how we would go about it, and what it would cost.
Salary, bonuses, share schemes, pensions, ISAs, cash, property and debt. We gather all of it, including the workplace pension from two jobs ago and the cash that has sat in a current account for years.
A year-by-year cashflow forecast of your income, spending and savings. It answers what a portfolio statement cannot: how much to save, whether you can afford the school fees or the bigger house, how much to keep for emergencies, and when you could stop working.
Your money in three pots: short term for what you need in the next few years, medium term for the goals on the horizon, and long term invested for growth. Built around your attitude to risk and managed in-house by our investment committee.
Pensions, ISAs, and your capital gains and dividend allowances used in full. Bonuses and contributions timed around the £100,000 line, and savings split between you and your partner where that helps, so more of what you earn stays invested.
A review at least once a year, and whenever a pay rise, a bonus, a new baby or a Budget changes the picture. In between, you can see everything in Helix and message your wealth manager directly.
 5-star rated, 100+ reviews
CEO of PlannerPal
Board member and former fintech VC
IQ client since 2020
“The approach to finance has been very personal, about what I care about most.”Watch more client stories →
What people ask when their income has grown faster than their plan.
Your income, savings and goals mapped over decades, so you know whether you are on course and what enough actually looks like for you.
The trade-off worked through with your real numbers: your mortgage rate, the tax relief available, likely returns and how much flexibility you want to keep.
Pension contributions, salary sacrifice, ISAs and allowances used together, with particular care if your income sits near £100,000 or your pension allowance is tapered.
Income protection, life and critical illness cover sized to what your family would actually need, and written in trust so a payout stays out of your estate.
The big commitments tested against the rest of your plan before you sign anything, so one decision does not quietly undo another.
The date you could choose to step back, and what it would take to bring it forward.
Three points where earning more can cost far more than you expect, and where planning makes the biggest difference.
You lose £1 of tax-free allowance for every £2 earned above £100,000, so that slice of income is taxed at an effective 60%. It can also cost you Tax-Free Childcare and funded childcare hours.
Above this line every pound is taxed at 45%. Bonuses and share awards that land here are where pension contributions and careful timing save the most.
Above this level of adjusted income, with threshold income over £200,000, the £60,000 annual allowance tapers down to as little as £10,000. Unused allowance from earlier years can often be carried forward.
Based on the rules for the 2026/27 tax year. Income tax thresholds are frozen until April 2031. Tax treatment depends on your circumstances and may change.
National Insurance relief on pension contributions made through salary sacrifice will be capped at £2,000 a year. Income tax relief is unchanged, so pensions remain one of the most tax-efficient homes for a high earner's money.
If you sacrifice bonuses or a large share of your salary, it is worth reviewing how you contribute before the rules change.
Financial planning for people whose income has grown faster than their plan. It starts with what you want your money to do, then works out how to save, invest, protect and structure it, rather than starting with a product.
For high earners that usually means three things: a clear view of whether you are building enough, an investment strategy with a job for every pound, and a tax plan that stops a strong salary being quietly eroded.
There is no single percentage that suits everyone. It depends on what you want to afford and when: school fees, a bigger home, stopping work early, helping the children later on.
A cashflow forecast turns those goals into a number. It shows what you need to put away each year, what you can comfortably spend, and how much to keep in cash for emergencies, then gets revisited as your income changes.
Your personal allowance falls by £1 for every £2 of adjusted net income above £100,000, so income between £100,000 and £125,140 is taxed at an effective 60%. Pension contributions, whether through salary sacrifice or personal contributions, reduce adjusted net income and can bring you back under the line. Gift Aid donations do the same.
Staying under £100,000 can also keep your eligibility for Tax-Free Childcare and funded childcare hours, which for a young family can be worth thousands of pounds a year on top.
Most people can pay in up to £60,000 a year, or 100% of their earnings if lower, with tax relief at their highest rate. If your threshold income is above £200,000 and your adjusted income above £260,000, that allowance tapers down to as little as £10,000.
Unused allowance from the previous three tax years can usually be carried forward, which is particularly useful in a year with a large bonus.
Usually both. A pension gives tax relief on the way in, at up to 45%, but the money is locked away until 57 from April 2028 and most withdrawals are taxed as income. An ISA gives no relief on the way in, but everything comes out tax-free whenever you want it.
Most higher earners use the pension for the long term and ISAs for the goals that come before retirement. The right balance depends on when you will need the money.
It depends on your mortgage rate, the tax relief you would get on pension contributions, the returns you could reasonably expect, and how much flexibility you want. Overpaying gives a guaranteed saving, but money paid off a mortgage is hard to get back out.
For many higher-rate taxpayers, extra pension contributions come out ahead because of the tax relief. We work through the trade-off with your own numbers rather than a rule of thumb.
From 6 April 2029, only the first £2,000 a year of pension contributions made through salary sacrifice will be free of National Insurance. Anything above that will attract National Insurance as if it were salary. Income tax relief is unchanged.
If you sacrifice bonuses or a large share of your salary, it is worth reviewing how you contribute before the change, and whether employer or personal contributions now suit you better.
The first meeting is free. After that it depends on whether you need a single piece of advice or ongoing planning and investment management. We publish the whole fee structure, so you can check the numbers before you speak to anyone.
Half an hour with an adviser about what you are earning, what you want to build, and how to get there.
Book a call